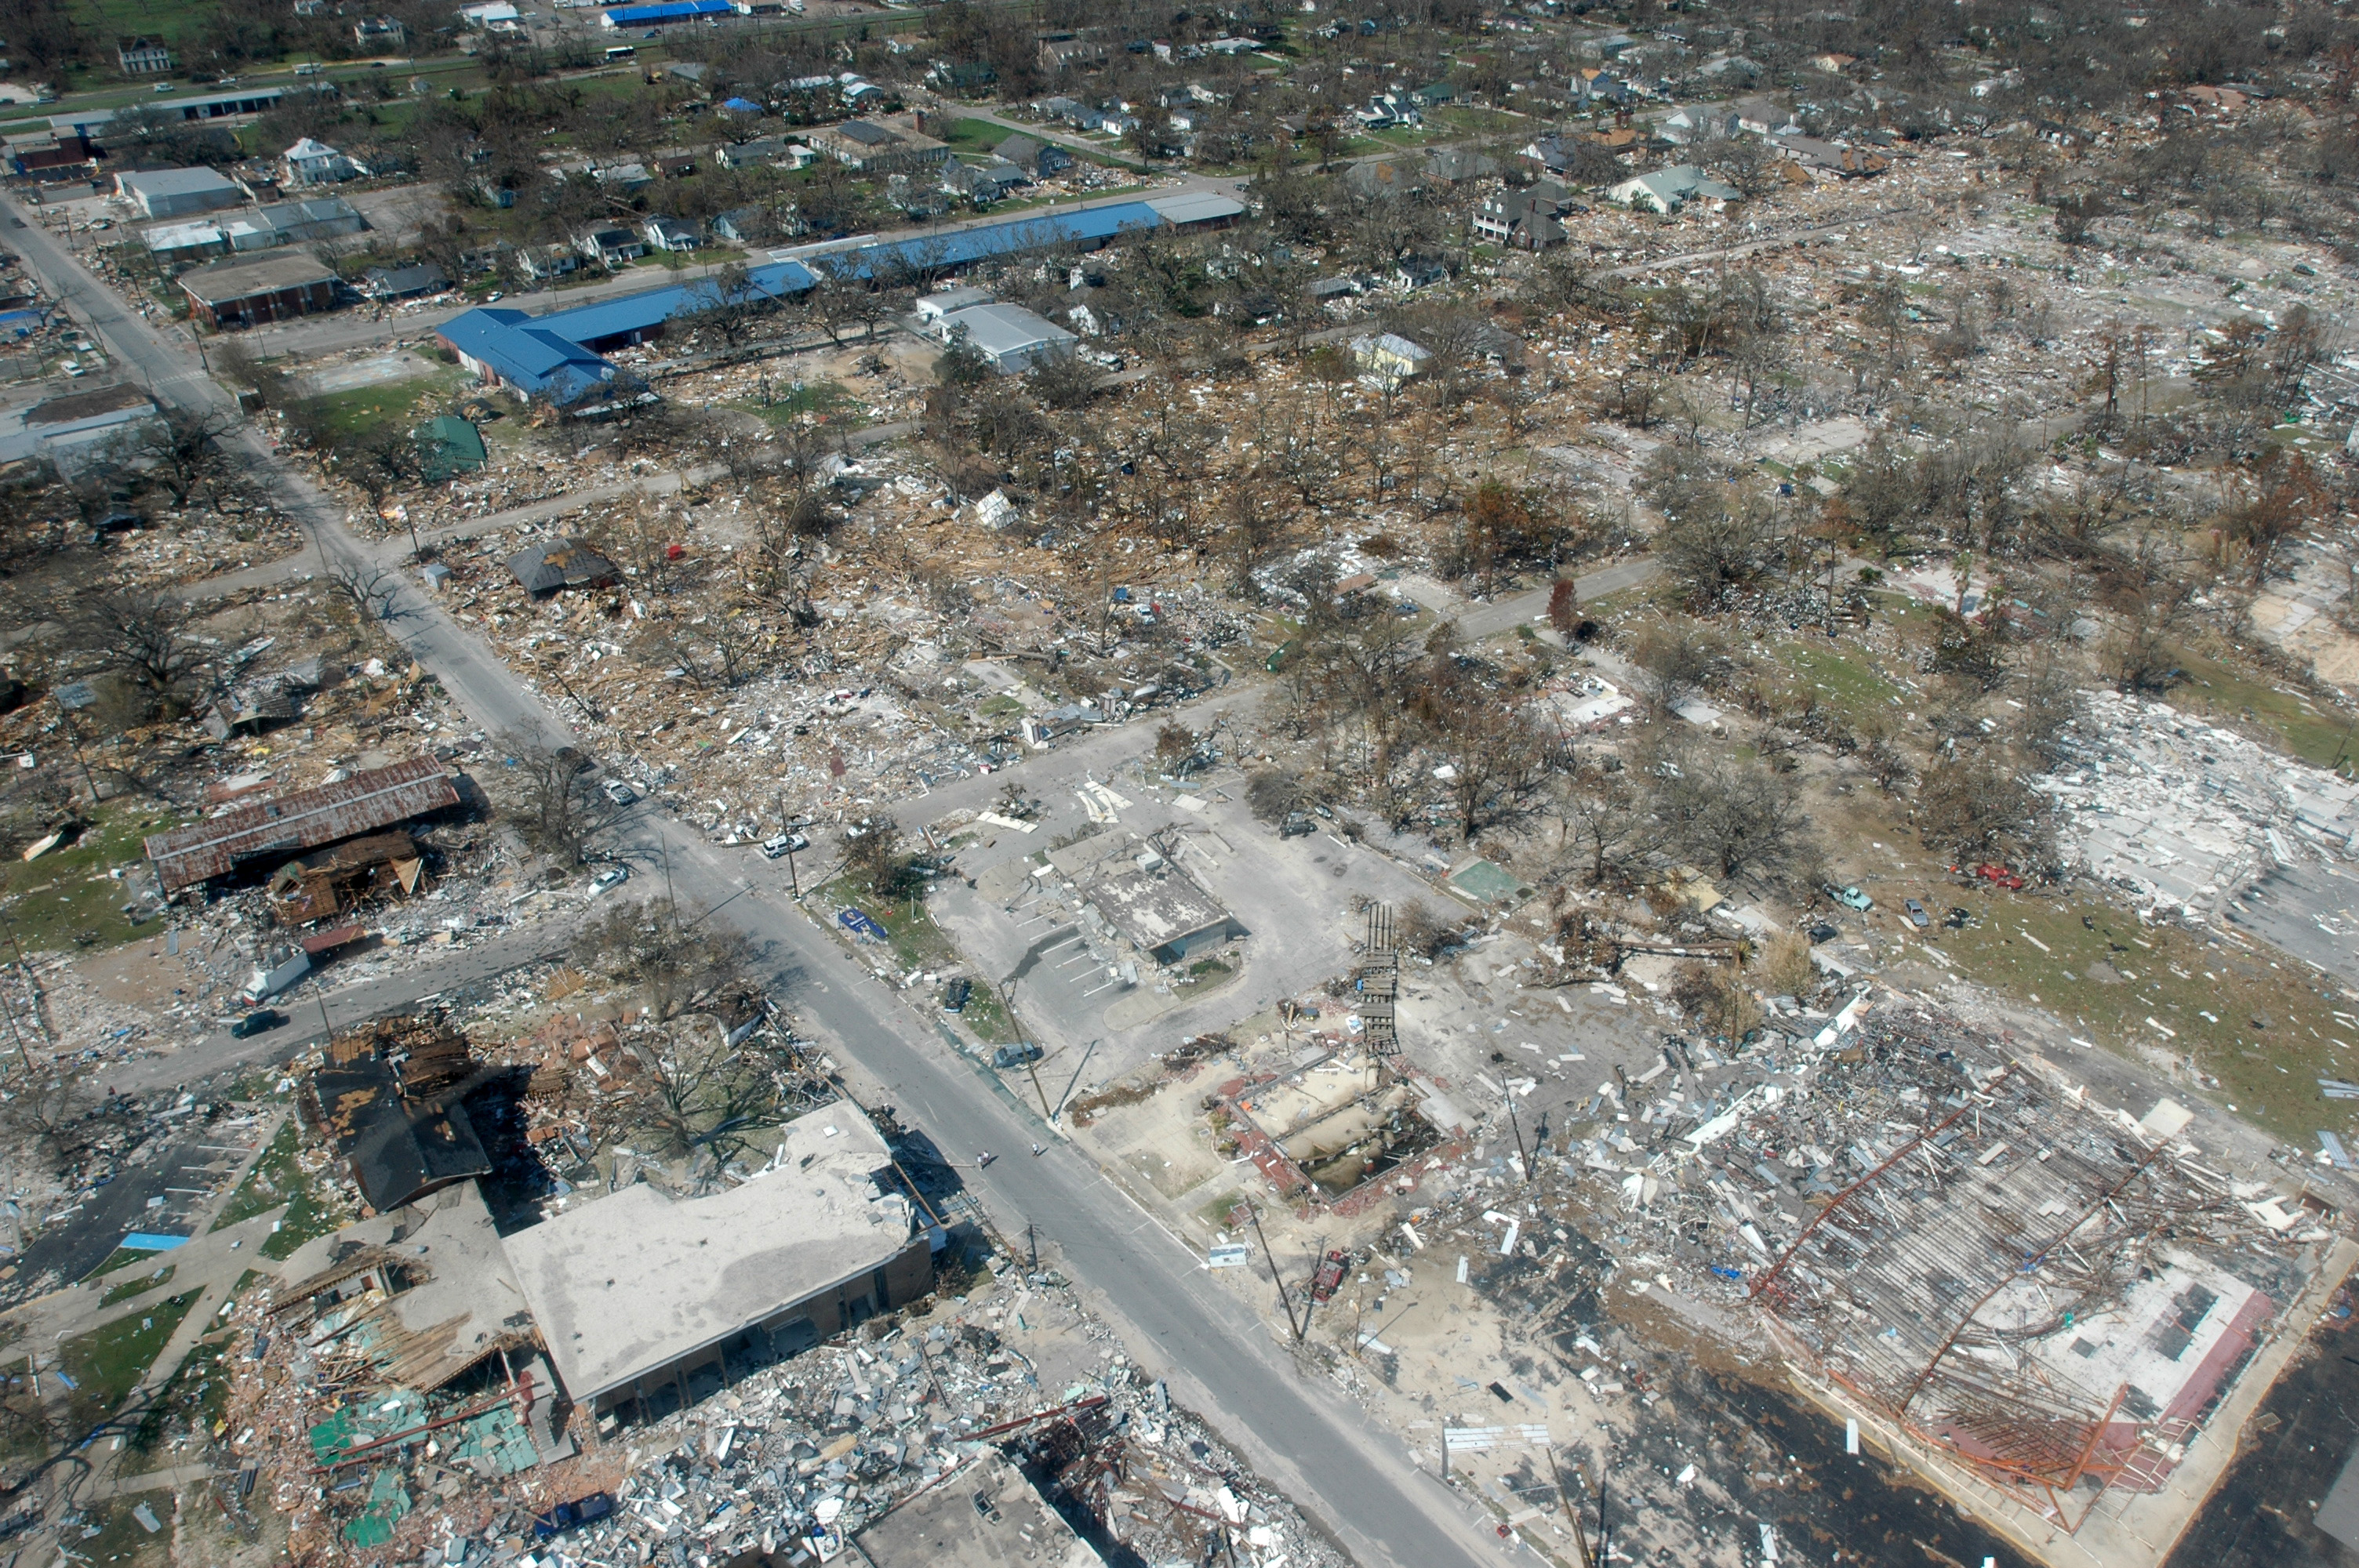
I know that sounds like a dumb question, but what for many of us is our biggest investment isn't a sure bet, Bankrate.com's Sheyna Steiner reported recently.
Far more people believe their homes are better investment than the stock market, even though the investment return historically is only half as large, she found. Home real estate prices aren't dropping as fast as several months ago, but they are still a long way from whippy.
Remember all that advice we heard about diversifying our investments to reduce risk? We've pretty much blown it, according to a study that researchers at Millman Inc. recently prepared for the Society of Actuaries. Many of have nearly 70 percent of our wealth tied up in one asset - our homes. And there are not many convenient ways to pull that money out, even in the best of times, writes MarketWatch's Robert Powell.
Even the optimists think we're maybe a year away from the bottom of the home and mortgage markets, writes Luke Mullins at US News.com. Meantime, we pulled so much wealth out of our homes when prices were rising that it may be a long time before our homes make us 'wealthy' again, says Bruce Bartlett at Forbes.
So what can a little guy do? Question everything, says Consumer Reports. What was good advice not long ago may be lame now. You may want to spiff up your place too. You may be there awhile if foreclosure doesn't get you.
Showing posts with label investing. Show all posts
Showing posts with label investing. Show all posts
Sunday, October 18, 2009

Wednesday, September 30, 2009
Bracing for a boomer bust?
The stock market has fallen more than 100 points since breakfast. It's my fault apparently.
U.S. News & World Report's Emily Brandon recently looked at a theory that baby boomers - I'm in the 1946-born first wave - threaten Wall Street by potentially cashing in our life savings en masse.
Things are a little more complicated than that, she found. And, as others have been reporting for years now, we boomers haven't been model savers. I think there's a more immediate argument, outlined in the Journal of the American Planning Association, that we may smother real estate recovery for awhile.
Others already resent how boomers' decisions are complicating their lives, AARP found in a 2004 survey. Now discussions of aging America and boomer wars are showing up more frequently in scholarly journals and elsewhere. Skirmishing already is beginning in the currently tough job market, reports Kiplinger.com.
But there may be some new career opportunities here too - putting on seminars about resolving generational conflict.
Friday, September 25, 2009
Fuzzy math: it's the cloud in our retirement savings silver lining
I'm expecting good news when my next retirement account statement hits the mail box.
My retirement savings, which were evaporating by $7,000 a day during the worst of last year's meltdown, have grown back more than $40,000 since then, according to what I've seen following the portfolio online. We'll get the official word after the third quarter closes next week.
Whoopee, right? Not so much. It's tempting to think that if you lose, say, 30 percent of your portfolio when markets fall, you make the money back when they rebound 30 percent later. The reality is your investment need to grow twice as much, or 60 percent in this case, just to break even, says Investopedia contributor Doug Rice. He does the math here.
There aren't any shortcuts back up the hill either, reports Michael Maiello at Forbes.com. He lists 11 you want to avoid. Meanwhile, Howtodothings.com contributor Marc Alexander lists some basic strategies you can follow. Basically you work harder and save more.
But there may be good news too. Kiplinger.com columnist Steven Goldberg reexamines some past recession market statistics and finds recovery may come faster than forecasters commonly think.
Wednesday, June 3, 2009
Set it. Forget it. Regret it.
Target-date mutual funds - those investment choices in your college savings plan and retirement account that automatically readjust to cut risk as time passes - went on the fritz big time in 2008.
Congress already plans next week to look into why that happened. Morningstar, the mutual fund rating organization, is ramping up its coverage of the funds.
Losses averaged 23 percent and in some cases exceeded 41 percent, according to research cited in a new Prudential white paper, Strengthening Target-Date Funds with Guarantees to Enhance Retirement Security, released today. The reason seems simple in hindsight. The 2008 market meltdown hit everything in its path like a Gulf Coast hurricane.
But vulnerability to a bear market is only one potential risk that comes with such funds, writes author Christine Marcks. Target-dates also contain what she called a zero balance risk and a purchasing power risk.
Cutting these risks - that you might run out of money too soon or that your retirement income won't keep up with inflation - may require additional action five to 10 years before reaching your target date, Marcks said.
You may have other choices too. But finding them will take more action on your part. Investments don't run well on autopilot.
Monday, February 9, 2009
If the boss blows out your 401(k) match...
Don't panic.
Free money is fun, but if your employer is among the growing number who are ending their matching contributions to workers' 401(k) plans, you can live without the extra cash.
But try to increase your own contributions to the plan to make up the difference. Remember, your goal here is to save for retirement. As some fellow personal finance bloggers discussed recently on bargaineering.com, even a non-matching plan may be better than an IRA, Roth IRA or other choices.
Here briefly are the key points to consider, experts say.
You can put more money, up to $16,500 currently, into a 401(k) than an IRA or Roth, now capped at $5,000 for many people. But 401(k)s usually offer fewer investment choices, which may be a bigger drawback in times like these.
Plus there is one gotcha to plan for. If your employer offers a plan, but you don't participate, your ability to deduct IRA contributions may be more limited.
Reducing your contribution should not be an option, except in maybe the most extreme circumstances.
So how do you come up with extra cash to do all this? Money maven Anthonty Delgado on e.how lists some popular ideas. Standup comic Vince Barnett on YouTube offers some alternatives using empty boxes, wheel chairs and other tools.
Friday, January 23, 2009
Holy cow, Grandma is beating Warren Buffett
You know the markets are in turmoil when stodgy old U.S. Savings Bonds are outperforming Wall Street.
Good old Series EE Savings Bonds are earning 1.3 percent now, which beats the pants off however many points the markets plunged today. Grandma's favorite alternative to spoiling the kids is even paying higher returns than Warren Buffett's Berkshire Hathaway, which is down to about $87,000 a share from the $140,000 neighborhood a year ago.
But the most rewarding Savings Bond to own right now is the Series I bond, which currently is paying 5.64 percent interest.
Series I bonds are the inflation-adjusted offerings that the Treasury launched just more than 10 years ago. Their rates, which are changed each May and November, are based heavily on what the Consumer Price Index did in the six months previously.
Right now those rates are about twice higher than many banks or credit unions pay because that $4 gas we bought last summer is cranked into the equation. That will change, of course. But cautious investors still might want to keep them in mind.
Savings Bonds pay interest for as long as 30 years, but can be cashed in sooner. There is a penalty - you lose three months' interest - if you redeem them within five years. You can pay taxes on the interest annually or defer it until either you cash them in or the 30 years is up. Uncle Sam sells them online or you can pick them up for as little as $25 and $50 at most banks and credit unions. Visit www.treasurydirect.gov for more details.
Subscribe to:
Posts (Atom)